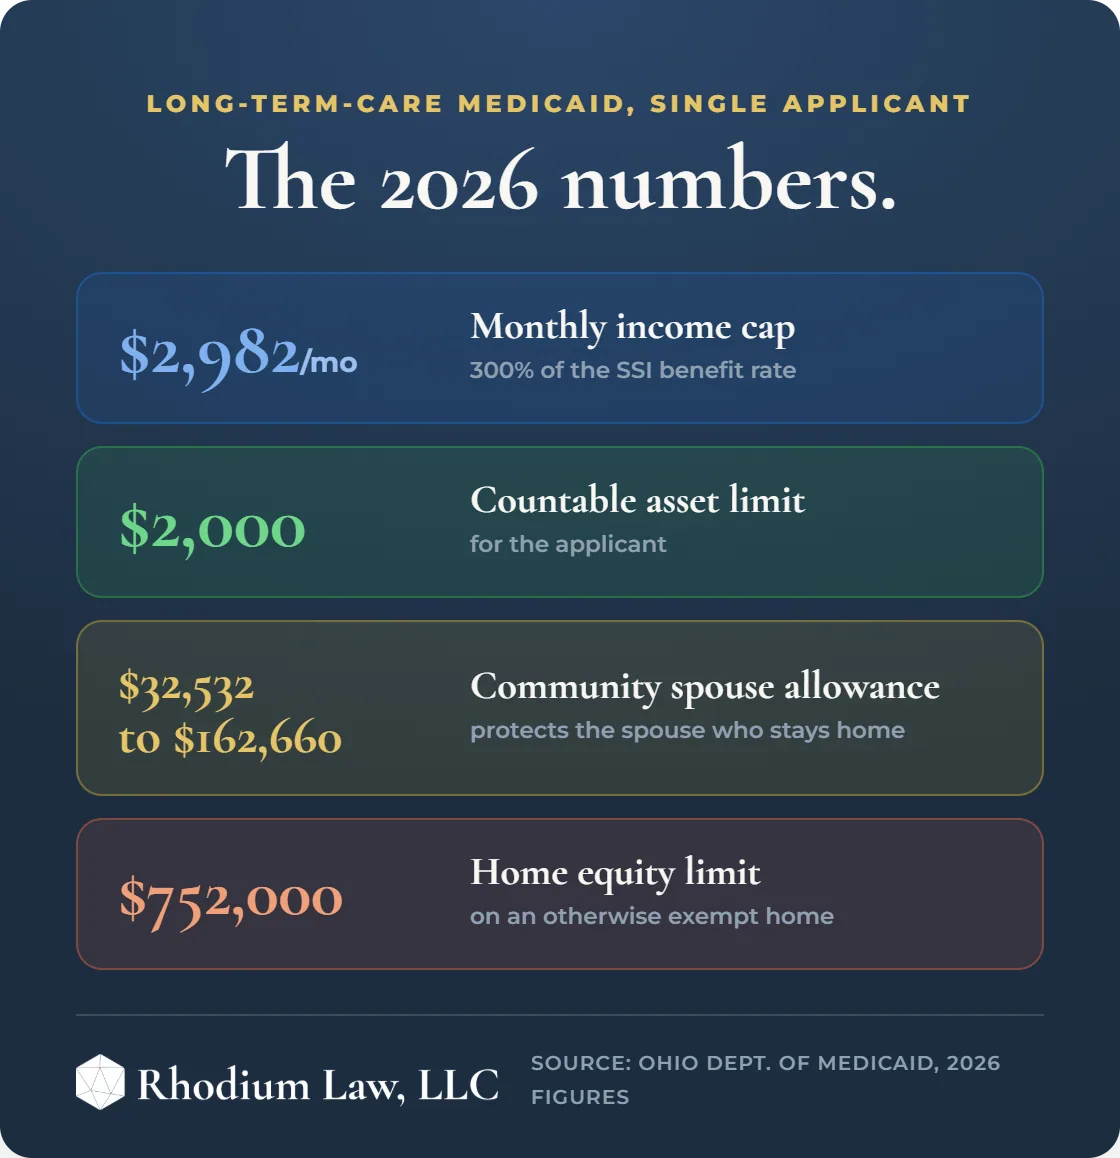
For 2026, a single applicant for Ohio’s long-term care Medicaid program, meaning nursing facility care or a home and community-based services waiver, must have monthly income under $2,982 and countable assets under $2,000. Ohio ties this figure to the federal SSI benefit rate published by the Social Security Administration. Other Medicaid categories use different income tests.
Ohio Medicaid income and asset limits for 2026, the Community Spouse Resource Allowance, the look back period, and how the rules affect long term care planning.
- What Is the Ohio Medicaid Income Limit for Long-Term Care in 2026? In 2026, a single applicant for Ohio long-term care Medicaid must have monthly income under $2,982.
- What Are the Asset and Resource Limits for Ohio Medicaid in 2026? For 2026, a single Ohio long-term care Medicaid applicant may hold no more than $2,000 in countable assets.
- What Is the Community Spouse Resource Allowance in Ohio? The Community Spouse Resource Allowance, or CSRA, lets the spouse of a Medicaid applicant who remains in the community keep a larger share of the couple’s countable assets.
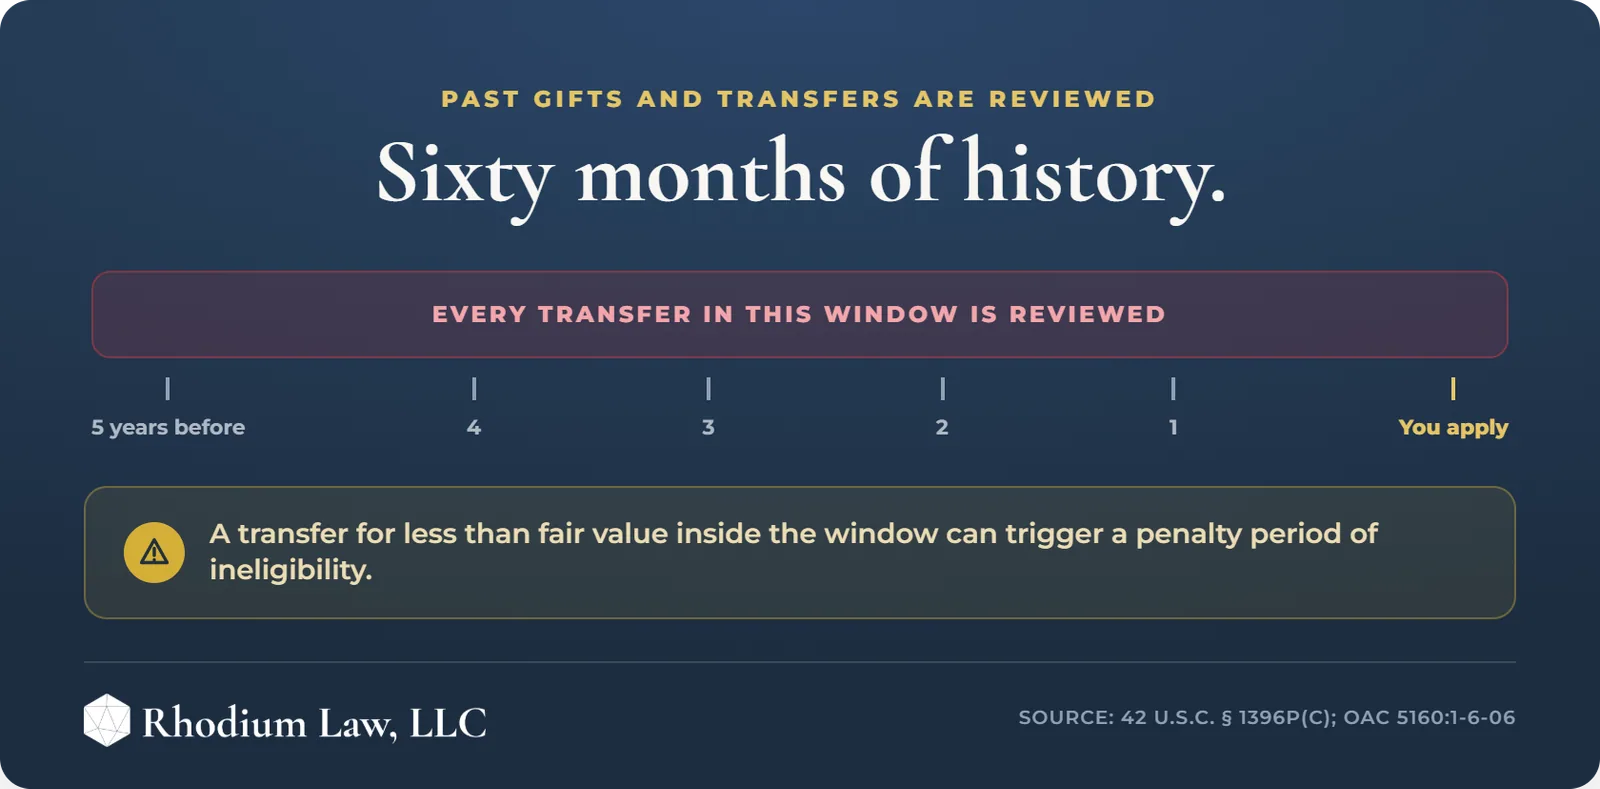
- What Is the Medicaid Look Back Period in Ohio? Ohio Medicaid reviews five years, sixty months, of an applicant’s financial transactions before a long-term care Medicaid application.
- How Does Home Ownership Affect Ohio Medicaid Eligibility? A Medicaid applicant’s primary home is generally exempt from the asset limit while the applicant, a spouse, or certain dependents live there.
Ohio Medicaid is not one program with one income limit. It is a set of categories, each with its own financial rules, administered by the Ohio Department of Medicaid under Ohio Revised Code Chapter 5163. For a family thinking about an aging parent’s long-term care, the category that matters most is long-term care Medicaid, and that is the focus of this post.
What Is the Ohio Medicaid Income Limit for Long-Term Care in 2026?
In 2026, a single applicant for Ohio long-term care Medicaid must have monthly income under $2,982. This figure equals three times the Social Security Administration’s 2026 SSI federal benefit rate of $994 per month, the federal formula Ohio Medicaid uses to set this income cap for institutional coverage.
The Social Security Administration raised the 2026 SSI federal benefit rate to $994 for an individual, up from $967 in 2025, following a 2.8 percent cost of living adjustment effective January 2026. Ohio Medicaid sets its long-term care income limit at three times that federal rate. An applicant whose income exceeds $2,982 is not automatically disqualified: a Qualified Income Trust, sometimes called a Miller Trust, can direct income above the limit into an irrevocable trust so it no longer counts toward eligibility. This income limit applies to the applicant only; a married applicant’s spouse who remains in the community is not held to the same figure, as the next section explains.
What Are the Asset and Resource Limits for Ohio Medicaid in 2026?
For 2026, a single Ohio long-term care Medicaid applicant may hold no more than $2,000 in countable assets. Countable assets include bank accounts, brokerage accounts, and most retirement accounts. Exempt categories include the applicant’s primary vehicle, household goods, and prepaid burial arrangements.
Ohio Medicaid counts most retirement account balances as an asset unless the applicant is drawing required distributions in a form Medicaid treats as income rather than a resource. The federal resource limit for institutional Medicaid has held at $2,000 for a single applicant for a number of years, while the home, discussed further below, follows its own exemption rule. For a married couple where only one spouse applies, the non-applicant spouse’s resource allowance is calculated separately under the Community Spouse Resource Allowance.
What Is the Community Spouse Resource Allowance in Ohio?
The Community Spouse Resource Allowance, or CSRA, lets the spouse of a Medicaid applicant who remains in the community keep a larger share of the couple’s countable assets. For 2026, Ohio permits the community spouse to retain up to $162,660, or the full countable total if it falls below $32,532.
Federal spousal impoverishment rules set both the CSRA and a companion figure, the Minimum Monthly Maintenance Needs Allowance (MMMNA), which protects the community spouse’s income rather than assets. Ohio’s MMMNA for the period running July 1, 2026 through June 30, 2027 is $2,705 per month, with a shelter standard of $811.50 and a maximum spousal income allowance of $4,066.50. These figures update on a July to June cycle rather than the calendar year, which is why they sit alongside, rather than exactly inside, the 2026 income and asset limits above.

What Is the Medicaid Look Back Period in Ohio?
Ohio Medicaid reviews five years, sixty months, of an applicant’s financial transactions before a long-term care Medicaid application. Ohio Revised Code Section 5163.30 makes an institutionalized individual ineligible for a period of time if the individual or spouse transferred assets for less than fair market value during that window.
Ohio Revised Code Section 5163.30 governs this rule, sometimes called the improper disposition of assets provision. Transfers made more than five years before an application generally fall outside the look back and do not trigger a penalty period. The federal annual gift tax exclusion, which the IRS set at $19,000 per recipient for 2026, has no bearing on the Medicaid look back: a gift that is exempt from federal gift tax reporting can still count as an improper transfer under Ohio Medicaid rules. Families who plan an asset protection strategy well ahead of a long-term care need are working with a different set of tools than families who are already inside the look back window.

How Does Home Ownership Affect Ohio Medicaid Eligibility?
A Medicaid applicant’s primary home is generally exempt from the asset limit while the applicant, a spouse, or certain dependents live there. If no one meeting those conditions occupies the home, Ohio applies a home equity limit of $752,000 for 2026, and equity above that figure counts toward the asset limit.
Home equity is the home’s value minus any debt against it. Even where the home is exempt during the applicant’s Medicaid eligibility, Ohio Department of Medicaid may seek reimbursement from the recipient’s estate after death under the Medicaid estate recovery program, addressed in Ohio Revised Code Section 5162.21. This is a separate rule from the eligibility limits above, and it is one reason families weigh the home’s treatment carefully as part of a broader elder law plan rather than in isolation.
What Is a Medicaid Spend Down in Ohio?
A Medicaid spend down is the process of reducing countable assets to Ohio’s $2,000 limit by converting them into exempt categories, such as home repairs, prepaid funeral arrangements, or paying down debt, rather than by gifting them away. A properly structured spend down does not trigger the five year look back penalty the way a gift does.
Spend down is one of several tools families use when a long-term care need has already arrived. Others include Medicaid Asset Protection Trusts funded well outside the look back window and annuity strategies for the community spouse. Executing any of these tools on an aging parent’s behalf typically requires a validly executed power of attorney, which is part of why Medicaid planning and incapacity planning tend to travel together. Rhodium Law’s article on planning for incapacity in Ohio covers the documents that make later Medicaid planning possible in the first place.
Frequently Asked Questions
What are the income limits for Medicaid in Ohio outside of long-term care?
Ohio Medicaid covers several categories beyond long-term care, including the Aged, Blind, and Disabled category and the Medicaid expansion for adults under a set percentage of the federal poverty guidelines. Each category applies a different income test than the $2,982 long-term care figure. Confirming which category applies comes before comparing income against any single limit.
How do I check my eligibility for Ohio Medicaid?
Ohio residents can review eligibility categories and start an application through the Ohio Benefits self-service system or by contacting the Ohio Department of Medicaid consumer hotline. Because long-term care Medicaid applies different income and asset rules than other Medicaid categories, confirming the correct category before applying helps avoid delays in the eligibility determination.
What are the resource limits for Ohio Medicaid eligibility?
For long-term care Medicaid, Ohio limits a single applicant’s countable resources to $2,000 in 2026. Married couples where one spouse applies use the Community Spouse Resource Allowance instead, letting the non-applicant spouse retain up to $162,660. Exempt resources, including the primary vehicle and certain prepaid expenses, do not count toward either limit.
What happens if my income is over the Ohio Medicaid long-term care limit?
An applicant whose income exceeds Ohio’s long-term care Medicaid limit is not automatically disqualified. A Qualified Income Trust, sometimes called a Miller Trust, can direct excess income into an irrevocable trust so it no longer counts against the limit. The trust must meet Ohio Medicaid’s requirements and typically requires legal drafting.
Does Ohio Medicaid count retirement account withdrawals as income?
Yes. Ohio Medicaid generally treats withdrawals from IRAs, 401(k)s, and similar retirement accounts as countable income in the month received. The account balance itself may also count as an asset unless the applicant is taking required distributions in a payout structure Ohio Medicaid treats as income rather than a resource.
What are the eligibility requirements for Medicaid in Ohio overall?
Ohio Medicaid eligibility depends on the category. Long-term care Medicaid requires income under $2,982 monthly, assets under $2,000, and a documented nursing facility level of care need. Other categories, such as the Medicaid expansion, use income tests tied to the federal poverty guidelines and do not apply an asset test at all.
Discuss your next step
A family’s care plan deserves more than a quick comparison with an income limit. If long-term care may be approaching, begin reviewing the full financial picture before making an application or changing ownership of assets. Take the first step by scheduling a complimentary 15-minute Strategy Session with Intake Services, so we can learn what matters to you and discuss the next step.