No. Ohio has no state inheritance tax and no state estate tax. Ohio repealed its estate tax for deaths on or after January 1, 2013, under House Bill 153, and the state has never imposed a tax on the person who inherits property. Federal estate tax may still apply, but only to very large estates under current law.
Ohio has no inheritance tax and repealed its state estate tax in 2013. Learn what that means for Ohio families, where federal estate tax can still apply, and what to review in your plan.
- Does Ohio Have an Estate Tax? No.
- How Much Is Inheritance Tax in Ohio? Ohio inheritance tax is zero, because Ohio does not have an inheritance tax.
- Inheritance Tax Versus Estate Tax: What Is the Difference? An estate tax and an inheritance tax are not the same tax under a different name.
- What if You Inherit Property from Someone in Another State? An Ohio resident does not owe Ohio tax on an inheritance.
- Does the Federal Estate Tax Apply to Ohio Families? Only above the federal exclusion amount.
Ohio families searching this question are usually asking about two different things at once: whether Ohio itself taxes what passes at death, and whether anyone, at any level of government, taxes it. Both questions have clear answers, and they are different questions with different rules.
Does Ohio Have an Estate Tax?
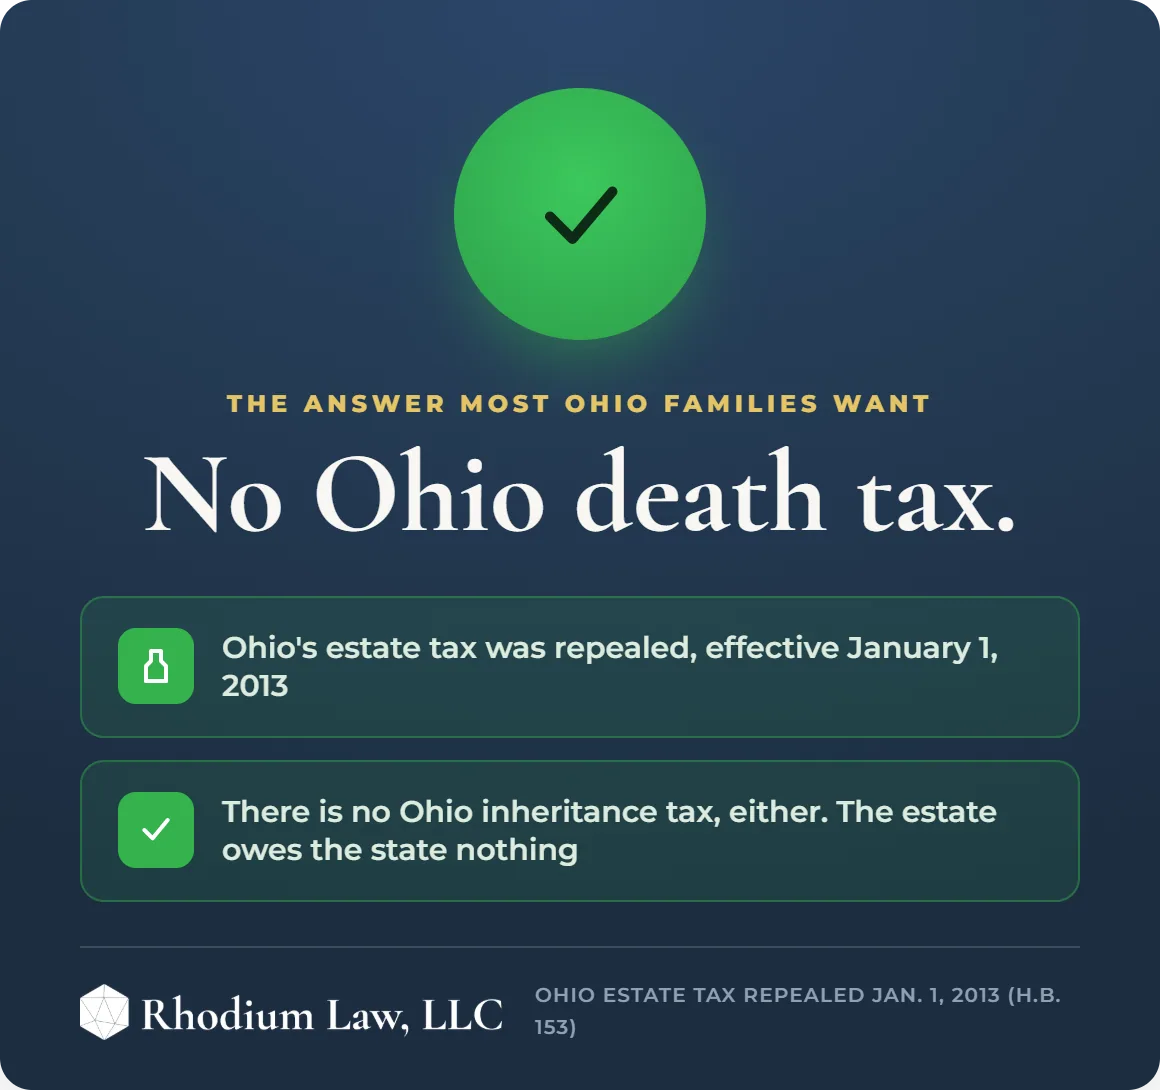
No. Ohio repealed its state estate tax effective January 1, 2013, when House Bill 153 (129th Ohio General Assembly) eliminated former Ohio Revised Code Chapter 5731. Estates of Ohio residents who die on or after that date owe no state estate tax, regardless of size.
Ohio once taxed estates directly. The Ohio General Assembly passed House Bill 153 in 2011. House Bill 153 repealed Ohio’s estate tax for deaths occurring on or after January 1, 2013. Before repeal, the Ohio Department of Taxation applied the tax to estates above a set dollar threshold, with the estate itself, not the heirs, responsible for paying it. Since 2013, that threshold and that tax no longer exist in Ohio.
How Much Is Inheritance Tax in Ohio?
Ohio inheritance tax is zero, because Ohio does not have an inheritance tax. No percentage, bracket, or exemption applies to what an Ohio resident inherits from another Ohio resident’s estate. The zero rate applies regardless of the relationship between the deceased person and the beneficiary, and regardless of how much property changes hands.
Ohio does not tax inheritances. Several states once taxed inheritances broadly in recent years. Five of those states still tax inheritances as of 2026: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Iowa completed a multi-year phase-out of its inheritance tax, reaching a zero rate for all beneficiaries by January 1, 2025. Ohio has never been on that list.
Inheritance Tax Versus Estate Tax: What Is the Difference?
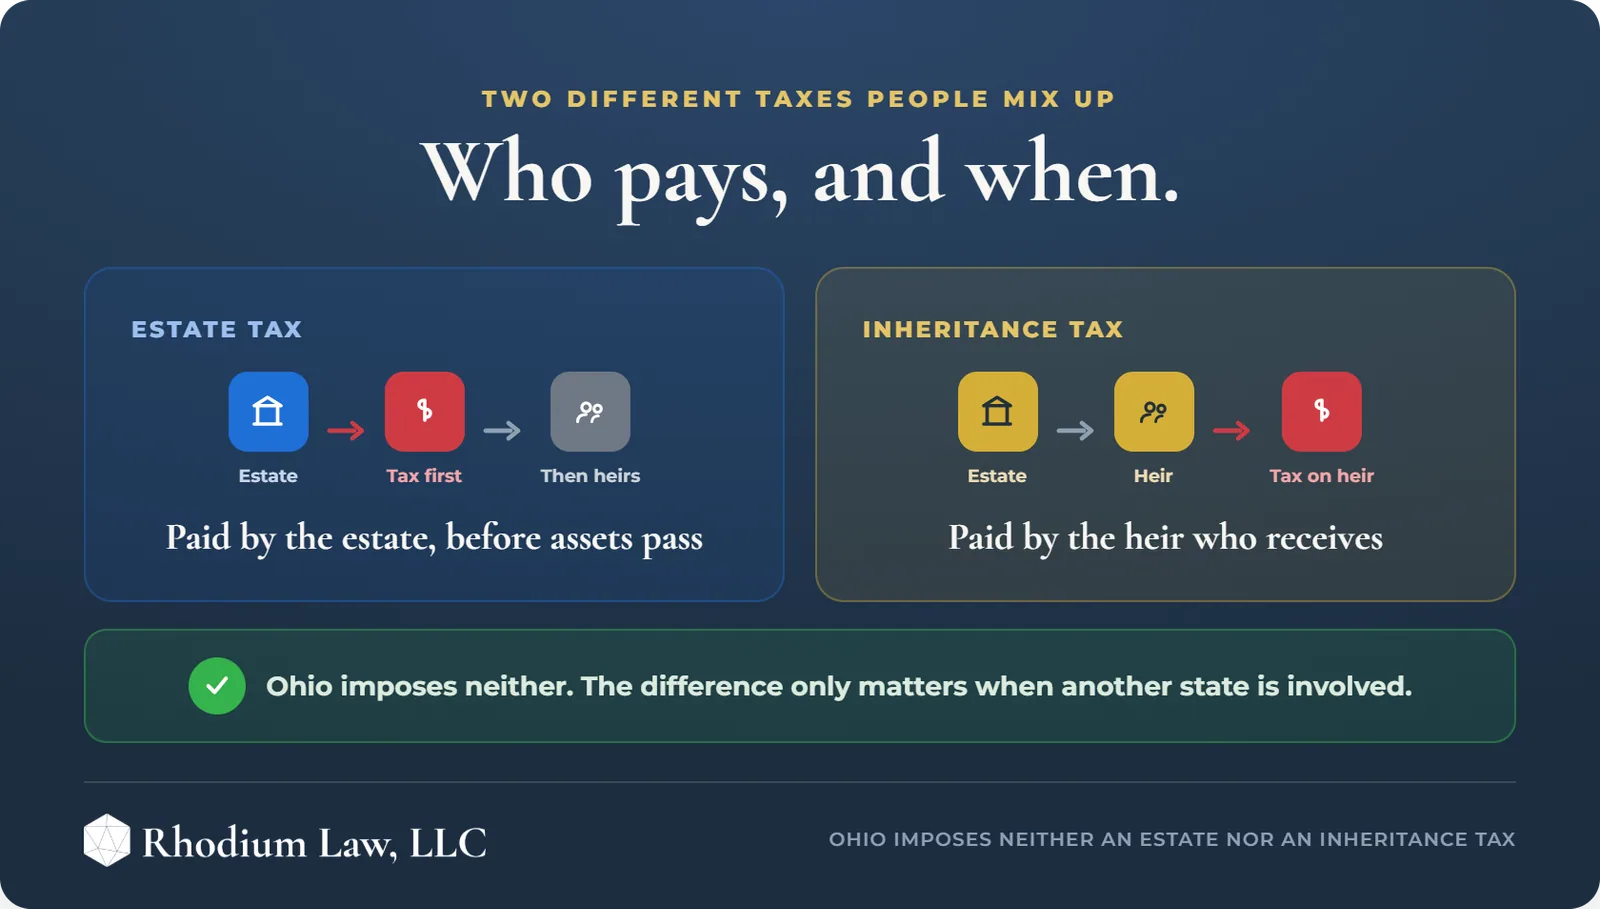
An estate tax and an inheritance tax are not the same tax under a different name. They tax different parties at different points in the transfer of property.
An estate tax is imposed on the estate. The estate pays the tax, out of estate assets, before property reaches the beneficiaries. The federal estate tax works this way, under 26 U.S.C. section 2001. An inheritance tax is imposed on the recipient. The beneficiary pays the tax personally, after receiving the inheritance, often at a rate that depends on the beneficiary’s relationship to the deceased person. Ohio imposes neither.
What if You Inherit Property from Someone in Another State?
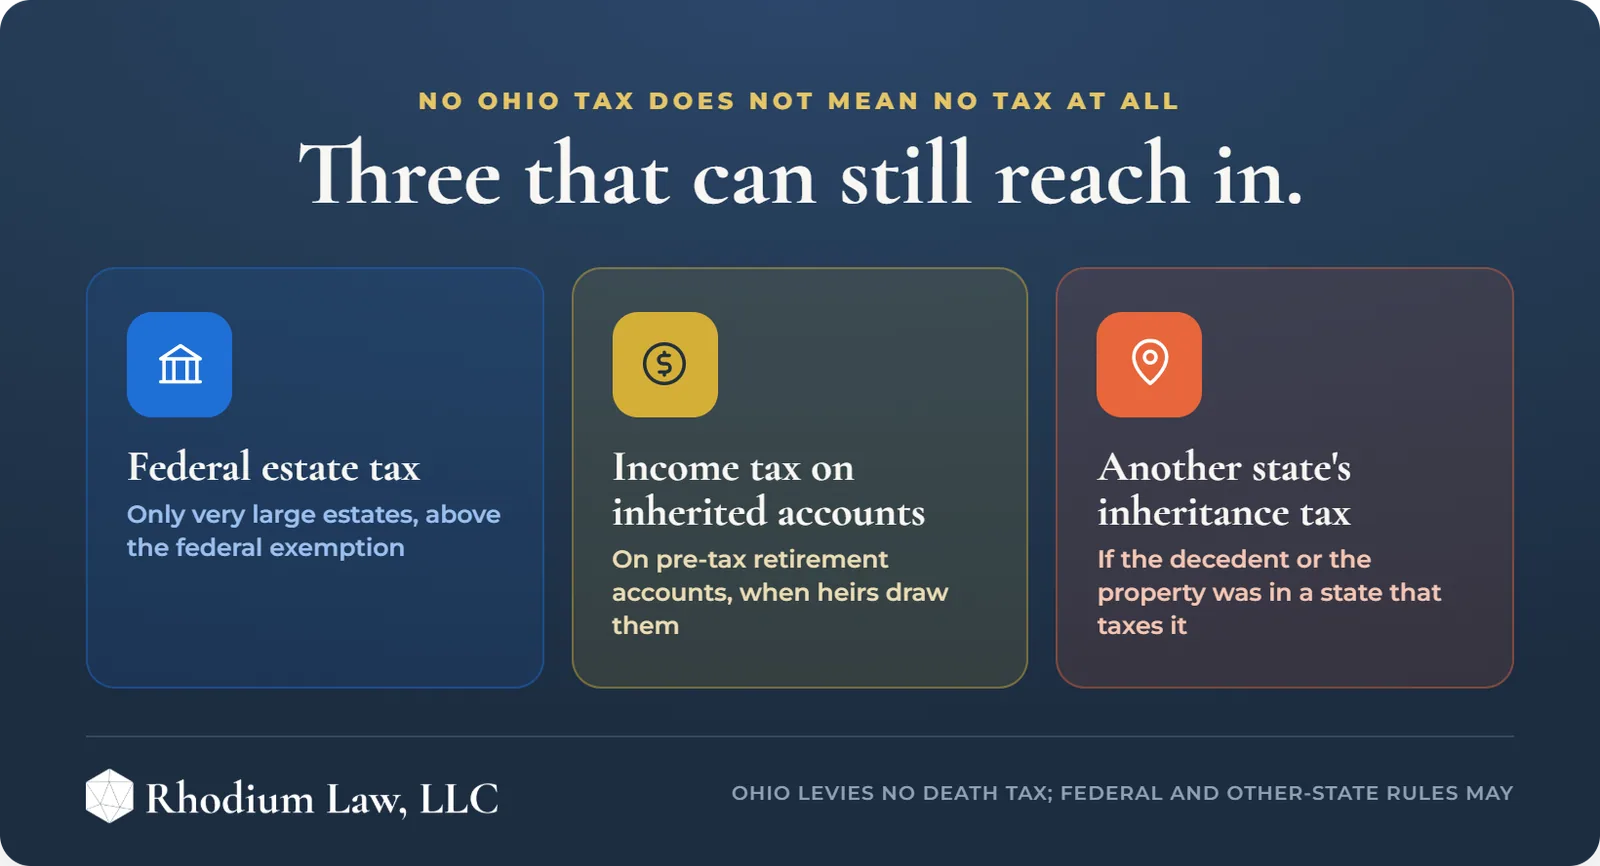
An Ohio resident does not owe Ohio tax on an inheritance. If the person who died lived in a state that still taxes inheritances, that state’s law, not Ohio’s, controls. As of 2026, five states impose an inheritance tax: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania.
Inheritance tax generally follows the decedent’s state of residence and the location of certain property, not the beneficiary’s home state. An Ohio resident who inherits from a parent who lived and died in Pennsylvania may owe Pennsylvania inheritance tax on that inheritance, calculated under Pennsylvania’s rules, even though the same resident would owe nothing to Ohio on an inheritance from an Ohio estate. The beneficiary’s Ohio residency does not exempt the inheritance from another state’s tax.
Does the Federal Estate Tax Apply to Ohio Families?
Only above the federal exclusion amount. The federal estate tax is imposed under 26 U.S.C. section 2001 on a decedent’s taxable estate, but no tax is owed on an estate valued below the exclusion amount set under 26 U.S.C. section 2010(c)(3).
Congress sets the federal exclusion amount, and it changes over time. The IRS set the basic exclusion amount at $15,000,000 per individual for estates of decedents dying in calendar year 2026, up from $13,990,000 in 2025. A married couple can generally combine both spouses’ exclusions with proper planning. Most Ohio estates fall well under this threshold, which means most Ohio families owe no federal estate tax either. Families whose combined estate approaches or exceeds the exclusion amount are the ones for whom federal estate tax planning becomes a real, current consideration rather than a background fact.
What Happens to the Tax Basis of Inherited Property in Ohio?
Inherited property is not taxed as income to the person who receives it. Inheritances are not treated as taxable income under federal income tax law. Separately, the tax basis of most inherited property is adjusted to its fair market value on the date of the decedent’s death, a rule commonly called the step-up in basis.
The step-up in basis matters most for appreciated assets, such as stock held for many years or real estate that has risen in value. When the recipient later sells stepped-up property, the recipient generally pays capital gains tax only on appreciation that occurred after the date of death, not on the gain that built up during the decedent’s lifetime. This is one reason a plan built around a properly funded living trust often treats what passes at death differently from what is given away during life.
What This Means for Your Estate Plan
For most Ohio families, the absence of a state estate tax and a state inheritance tax removes an entire layer of concern from the planning conversation. What typically remains is not a tax question at all. It is a set of practical questions: who decides if a person becomes incapacitated, how quickly and privately property reaches the people it is meant for, and whether that property is protected once it arrives.
For families whose planning is still driven mainly by tax exposure, the conversation usually covers:
- Probate avoidance, which is about timing and privacy, not tax
- Incapacity planning, which is about who is authorized to act during life
- Asset protection, which is about insulating property from creditors, not tax
- Ongoing trust management for beneficiaries, which governs how and when property reaches them
For families approaching or exceeding the federal exclusion amount, the conversation typically adds annual gifting strategies, use of the lifetime federal exemption, and irrevocable trust structures designed around the federal estate tax framework rather than any Ohio tax. A full estate plan accounts for both layers, the one that no longer exists in Ohio and the one that still exists federally, so nothing is left assuming a rule that changed over a decade ago.
Frequently Asked Questions
Does Ohio have an inheritance tax in 2026?
No. Ohio has never imposed a tax on the person who receives an inheritance, and that remains true in 2026. Only the federal government taxes estates, and only above a high exclusion amount. An Ohio resident inheriting from another Ohio resident’s estate owes no state tax on that inheritance, regardless of the amount received.
Is there an inheritance tax in Ohio?
No, Ohio does not have an inheritance tax. As of 2026, five other states still tax inheritances: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. An Ohio resident inheriting from an estate in one of those states may still owe that state’s tax, even though Ohio itself imposes none.
What is the inheritance tax in Ohio?
There is no inheritance tax rate in Ohio, because the state does not levy one. Ohio’s estate tax, a related but different tax once paid by the estate rather than the heir, was repealed for deaths on or after January 1, 2013. Nothing has replaced either tax since that date.
What is the estate tax in Ohio?
Ohio has no estate tax. The state repealed its estate tax under House Bill 153, effective for deaths on or after January 1, 2013. Before that date, Ohio taxed estates above a set threshold. Since 2013, only the federal estate tax can apply to an Ohio decedent’s estate, and only above the federal exclusion amount.
Discuss your next step
You should be able to plan an inheritance with a clearer understanding of the questions involved. Before making a substantial transfer or handling an estate, start coordinating the ownership, administration, and tax considerations. Take the first step by scheduling a complimentary 15-minute Strategy Session with Intake Services, so we can learn what matters to you and discuss the next step.
Ohio’s tax history can create confusion, so it helps to understand the difference between an estate tax and an inheritance tax.