A Medicaid trust is an irrevocable trust used to help a person qualify for Ohio Medicaid coverage of long-term care while still directing how the trust’s remaining assets are eventually used. Because Ohio applies a five year look back period before an application, a Medicaid trust generally needs to be funded well ahead of any anticipated care need, not created in response to one.
Learn how a Medicaid trust works under Ohio law, including the five year look back period, estate recovery, and how it fits an estate plan.
- What Is a Medicaid Trust? A Medicaid trust is an irrevocable trust that removes assets from a person’s countable resources so that person may become eligible for Ohio Medicaid coverage of long-term care, while the trust document still controls how those assets are managed and eventually distributed.
- How Does a Medicaid Asset Protection Trust Work in Ohio? An Ohio Medicaid asset protection trust works by having the grantor transfer assets, often a home or investment accounts, into an irrevocable trust managed by a trustee, who is frequently an adult child or another family member named in the trust.
- Does Putting Your Home in a Trust Protect It From Medicaid? A home transferred into a properly drafted and properly timed irrevocable Medicaid trust is generally excluded from the grantor’s countable resources and is shielded from Ohio’s Medicaid estate recovery program, provided the transfer occurred outside the five year look back window and the trust meets Ohio’s requirements for an irrevocable trust.
- What Is the Look Back Period for a Medicaid Trust in Ohio? Ohio, like every other state, reviews the 60 months, or five years, preceding a Medicaid application for transfers made for less than fair value.
- What Are the Disadvantages of a Medicaid Trust? The main disadvantages of a Medicaid trust are the loss of direct control over the transferred assets, the five year timing requirement, and the fact that assets remaining in the trust at the beneficiary’s death are typically subject to Medicaid’s reimbursement claim up to the value of benefits paid.
Long-term care planning is easy to overlook, yet it sits at the center of many Ohio estate plans. As the National Institute on Aging points out, most people worry about the possibility of needing long-term care but have limited tools available to prepare for it in advance. Medicare covers a range of medical needs but does not generally cover extended long-term care, and private long-term care insurance is not available to everyone or does not cover every scenario. For many families, a properly timed Medicaid trust becomes one part of a broader elder law and estate planning strategy.
What Is a Medicaid Trust?
A Medicaid trust is an irrevocable trust that removes assets from a person’s countable resources so that person may become eligible for Ohio Medicaid coverage of long-term care, while the trust document still controls how those assets are managed and eventually distributed.
Federal law governs how trusts are treated for Medicaid eligibility purposes. Under 42 U.S.C. Section 1396p(d), an irrevocable trust funded by the applicant is generally treated differently from a revocable trust, and the specific terms of the trust determine how much of it counts as an available resource. Ohio applies this federal framework through Ohio Administrative Code 5160:1-3-05.2, which defines how the Ohio Department of Medicaid classifies and treats trusts when it reviews an application.
A Medicaid trust shares some features with a special needs trust, since both are designed to preserve eligibility for a means-tested benefit. Unlike most special needs trusts, however, a Medicaid trust is typically funded by the same person it is meant to protect, and it is created as part of that person’s own long-term care and estate planning, not on behalf of someone else.
How Does a Medicaid Asset Protection Trust Work in Ohio?
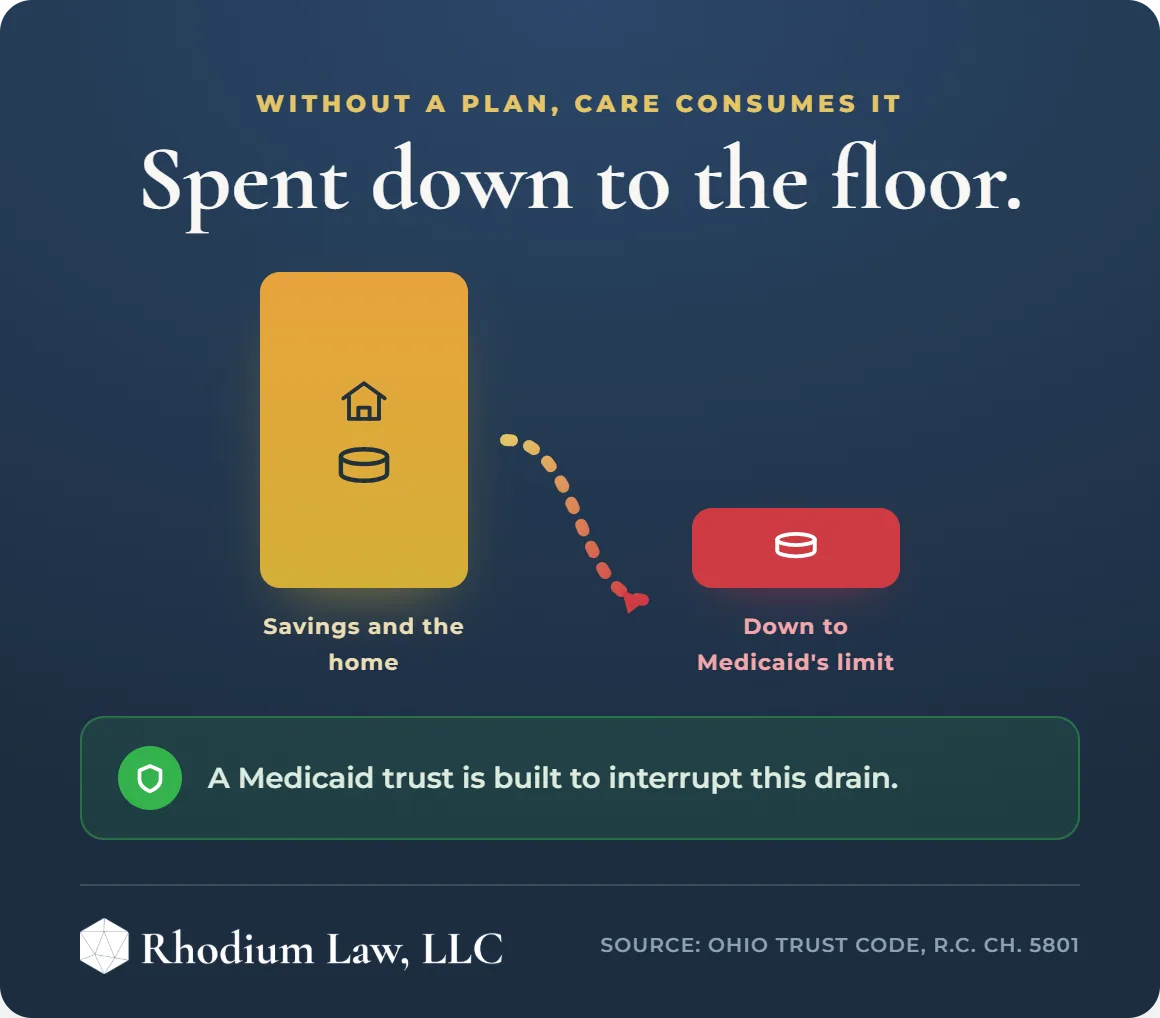
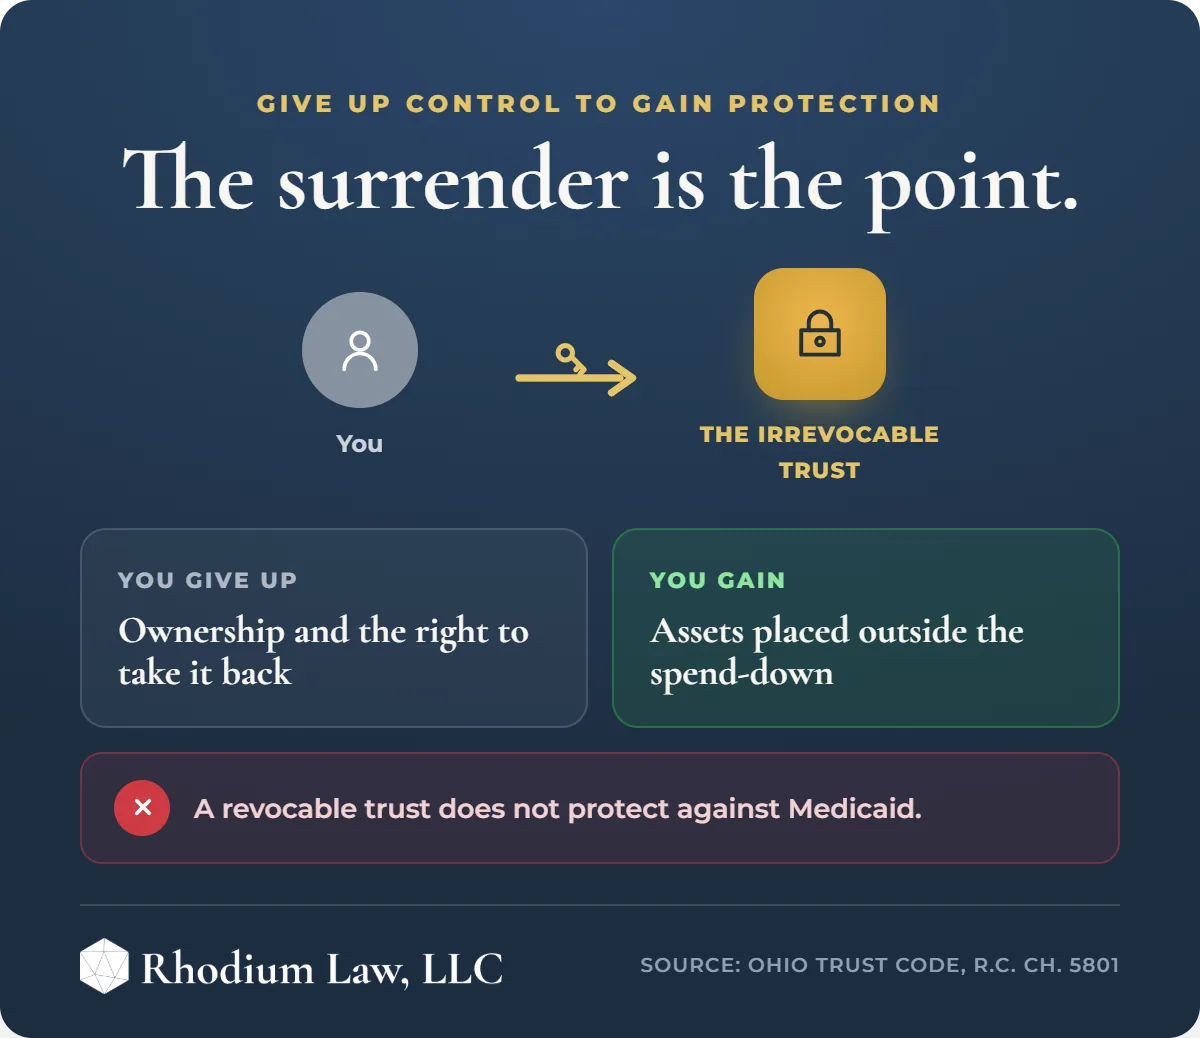
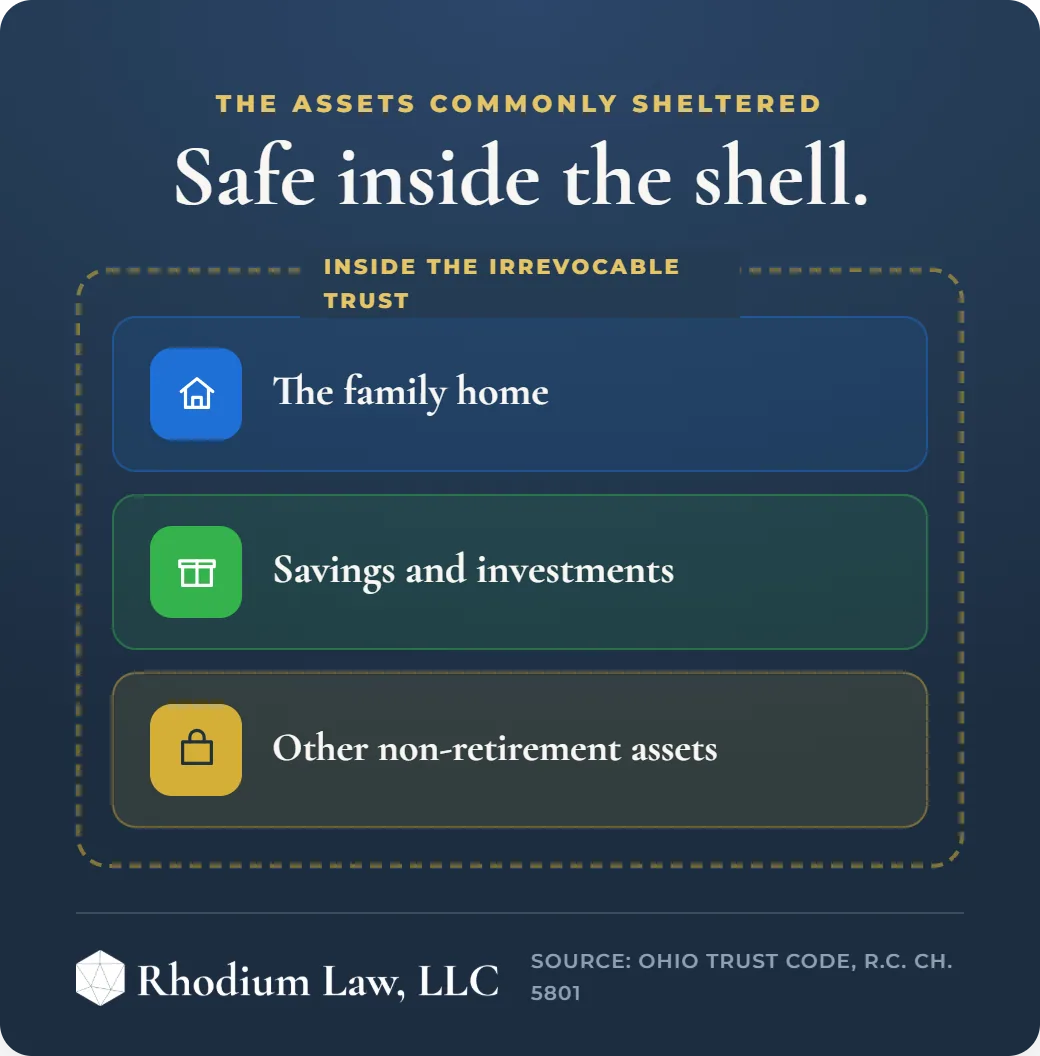
An Ohio Medicaid asset protection trust works by having the grantor transfer assets, often a home or investment accounts, into an irrevocable trust managed by a trustee, who is frequently an adult child or another family member named in the trust. The grantor gives up direct control and ownership of those assets so they fall outside Medicaid’s countable resource calculation.
The trustee holds legal title to the trust property and administers it according to the trust terms for the grantor’s benefit and, later, for the benefit of the remainder beneficiaries named in the trust. Under Ohio Administrative Code 5160:1-3-05.2, whether trust assets count toward Medicaid eligibility depends on whether the grantor retained any circumstance under which trust funds could be paid to or for the grantor’s benefit. A trust drafted so that no such payment can occur is treated differently than one that preserves that access, which is why careful drafting and proper trust funding matter as much as the decision to create the trust itself.
Does Putting Your Home in a Trust Protect It From Medicaid?
A home transferred into a properly drafted and properly timed irrevocable Medicaid trust is generally excluded from the grantor’s countable resources and is shielded from Ohio’s Medicaid estate recovery program, provided the transfer occurred outside the five year look back window and the trust meets Ohio’s requirements for an irrevocable trust.
Ohio’s Medicaid estate recovery program, authorized under Ohio Revised Code 5162.21, allows the state to seek reimbursement from a deceased Medicaid recipient’s probate estate for long-term care benefits the program paid on that person’s behalf. A home that remains titled in the individual’s own name at death typically passes through probate and is exposed to that recovery claim. A home held in an irrevocable Medicaid trust, by contrast, generally is not part of the probate estate, which is the main reason families consider this strategy as part of broader asset protection planning.
What Is the Look Back Period for a Medicaid Trust in Ohio?
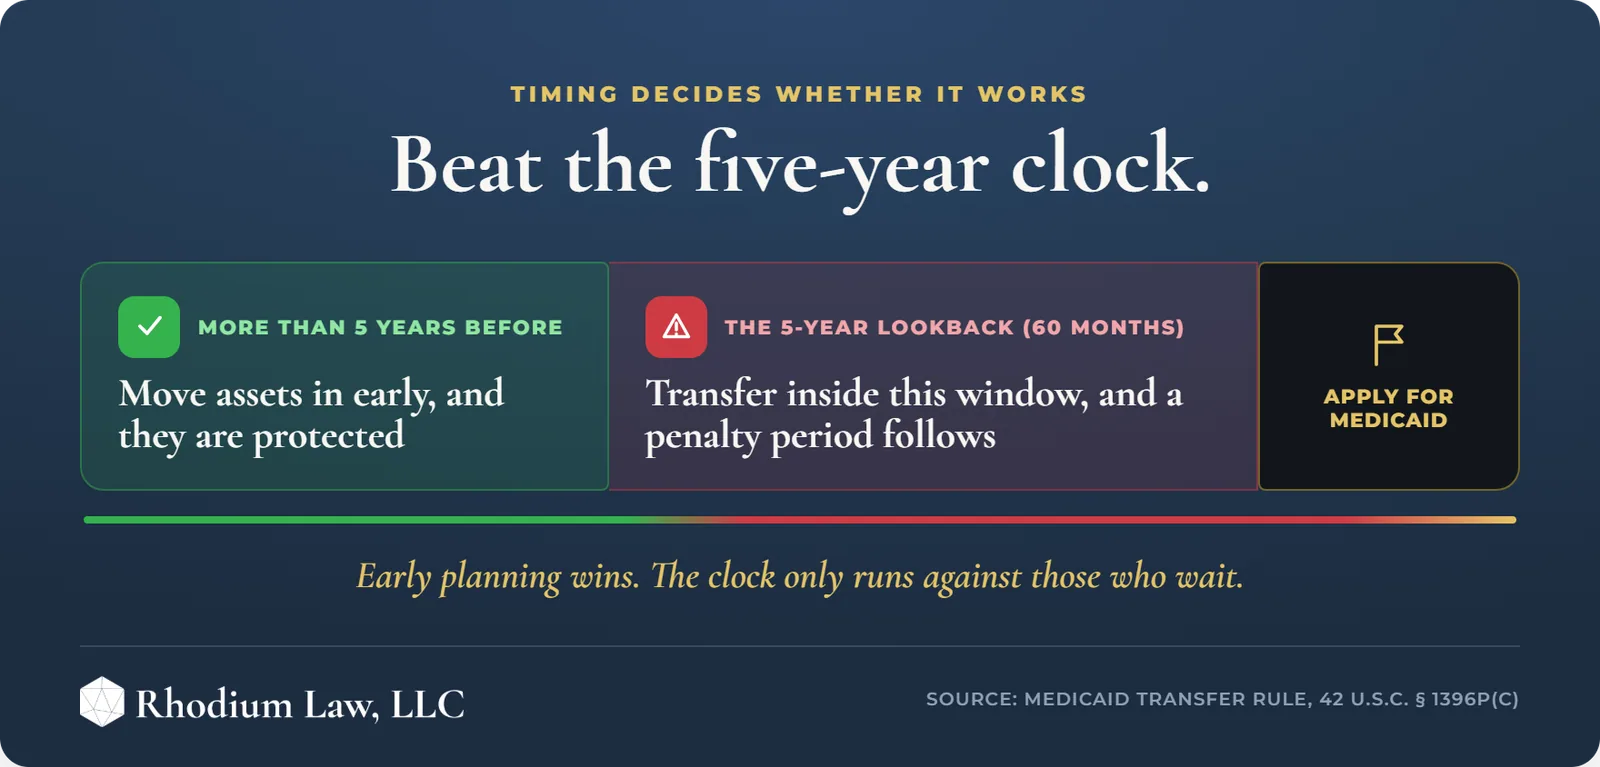
Ohio, like every other state, reviews the 60 months, or five years, preceding a Medicaid application for transfers made for less than fair value. Funding a Medicaid trust inside that five year window can trigger a penalty period during which Ohio Medicaid will not pay for long-term care, even though the applicant otherwise qualifies.
This look back rule comes from federal law under 42 U.S.C. Section 1396p(c), which Ohio Medicaid applies when it evaluates transfers and trust funding as part of an application. Because a Medicaid trust is irrevocable and the look back period cannot be shortened after the fact, the trust generally needs to be created and funded years before a person expects to need long-term care, not after a health event has already occurred. This timing requirement is one of the clearest reasons Medicaid trusts belong in a person’s broader asset protection plan rather than in a crisis response.
What Are the Disadvantages of a Medicaid Trust?
The main disadvantages of a Medicaid trust are the loss of direct control over the transferred assets, the five year timing requirement, and the fact that assets remaining in the trust at the beneficiary’s death are typically subject to Medicaid’s reimbursement claim up to the value of benefits paid.
An irrevocable Medicaid trust surrenders the grantor’s direct control over the transferred assets to the trustee, which means the grantor generally cannot reclaim the principal or unilaterally change the trust’s terms. Because the trust is irrevocable, a family that funds it and later decides the arrangement no longer fits their circumstances has limited options for reversing course. These tradeoffs are different from those of a revocable, or living trust, which offers flexibility and probate avoidance but does not shield assets from Medicaid’s resource count, since the grantor of a revocable trust retains the ability to reach the trust property.
How Much Does a Medicaid Asset Protection Trust Cost to Set Up?
The cost of setting up a Medicaid asset protection trust depends on the complexity of the estate, the number and type of assets being funded into the trust, and the attorney’s drafting and funding work, so the fee is a conversation to have directly with an attorney rather than something to estimate from a general figure.
Because a Medicaid trust is irrevocable and must be funded correctly to work as intended, the drafting fee typically reflects both the trust document itself and the work of retitling assets, such as real estate, into the trust’s name. Families often weigh that cost against the value of the assets the trust is designed to protect and against the potential cost of paying privately for long-term care without any planning in place, which the National Institute on Aging notes can accumulate quickly over an extended period of care.
Frequently Asked Questions
Can Medicaid take your house if it is in a trust?
If a house was transferred into a properly drafted irrevocable Medicaid trust outside the five year look back period, Ohio’s Medicaid estate recovery program generally cannot reach it, since the home is no longer part of the individual’s probate estate. A house still titled in the applicant’s own name remains exposed to recovery under Ohio Revised Code 5162.21.
Does a revocable trust protect assets from Medicaid?
No. A revocable, or living, trust allows the grantor to change or cancel the trust and reach its assets at any time, so Ohio Medicaid treats those assets as still available to the grantor. Only an irrevocable trust that meets Ohio’s requirements under Ohio Administrative Code 5160:1-3-05.2 can remove assets from Medicaid’s countable resource calculation.
Is an irrevocable trust protected from Medicaid?
An irrevocable trust can be protected from Medicaid’s resource count, but only if it is drafted so the grantor retains no circumstance under which trust funds could be paid back to the grantor. If any such access exists, Ohio Administrative Code 5160:1-3-05.2 treats that portion of the trust as an available resource.
What is a Qualified Income Trust, or Miller Trust, and how is it different from a Medicaid asset protection trust?
A Qualified Income Trust, sometimes called a Miller Trust, is used under Ohio Administrative Code 5160:1-6-03.2 to help an applicant whose monthly income exceeds Ohio’s Medicaid income limit still qualify for benefits. It addresses income, while a Medicaid asset protection trust addresses countable resources like a home or savings.
What is a pooled trust for Medicaid?
A pooled trust combines the funds of many individual beneficiaries for investment and administration purposes, while maintaining separate accounts for each person, and is typically managed by a nonprofit organization. Pooled trusts are most often used in disability planning contexts and function differently from an individually drafted Medicaid asset protection trust.
What are the current Ohio Medicaid income and asset limits?
Ohio Medicaid income and resource limits are updated periodically and are addressed in detail on Rhodium Law’s dedicated page covering current figures, since those numbers change more often than the trust rules described in this article. See Ohio Medicaid Income Limits for the current figures.
Discuss your next step
Preparing for care involves choices that can affect both your independence and the people you hope to support. Start discussing the timing and tradeoffs before transferring assets into a trust or applying for assistance. We invite you to schedule a complimentary 15-minute Strategy Session with Intake Services and begin the conversation about your goals and working with the firm.